

This is Part 2 of our cargo insurance series. Part 1 covered "all risk" coverage, forwarder insurance and loading damage.
The lesson that changed how shippers see general average
In 2018, fire broke out on the container ship Maersk Honam in the Arabian Sea. The owner declared General Average, and cargo owners, including those whose goods came through undamaged, had to post security worth 54% of their cargo's value (42.5% salvage security plus an 11.5% GA deposit) before their containers were released. In May 2021, General Average was declared again when the X-Press Pearl caught fire off Colombo, Sri Lanka.
Shippers with cargo insurance had their insurer post that security for them. Uninsured shippers had to find the cash themselves. They learned the hard way: cargo insurance myths aren't academic. They're bankruptcy risks.
Let's dismantle three more myths that sink supply chains.
Myth 4: "My policy covers delay"
Reality: Losses caused by delay are excluded, even when the delay was caused by an insured risk
Standard cargo policies, including the Institute Cargo Clauses, exclude loss, damage or expense caused by delay, even if the delay itself was caused by a risk the policy covers. The only carve-out is expenses payable under General Average.
Example: A container of electronic components is stuck at a congested transshipment port for three weeks. The heat and humidity cause the components to deteriorate, and the factory waiting for them halts its production line. The entire claim, both the production losses and the physical damage, is denied because the root cause was delay, an excluded peril.
Losses typically excluded under the delay clause
- Consequential losses: Lost sales, production line shutdowns, late delivery penalties.
- Transit costs: Demurrage, detention, and extra storage fees.
- Physical damage: Spoilage or degradation that results directly from the extended transit time.
How to fight back
- Delay in Start-Up (DSU) insurance, a specialized policy for project cargo, protects against financial losses when critical components don't arrive on time.
- IoT trackers help prove when damage occurred (before the delay or during it).
Myth 5: "Missing cargo = theft"
Reality: For insurers, no forced entry means no theft claim
Insurance policies make a critical distinction between "theft" and "mysterious disappearance," two events with very different outcomes for your claim.
- Theft requires evidence of a criminal act, like a broken seal or forced entry. It is generally covered.
- Mysterious disappearance is when cargo vanishes from a sealed, intact container. This is often excluded or subject to a high deductible because it points toward internal errors (like miscounting at origin) rather than an external crime.
| Theft (covered) | Mysterious disappearance (excluded) |
|---|---|
| Evidence of a broken or tampered container seal. | Seals are intact, but cargo is missing. |
| CCTV footage or witness reports of a break-in. | No physical evidence of intrusion. |
| A clear criminal event can be identified. | Loss is only discovered during the final count. |
The $800,000 vanishing act
A sealed container of iPhones arrived in Rotterdam weighing 50% less than it should. With no cut locks or signs of tampering, the insurer denied the theft claim, pointing instead to potential packing list errors at the origin facility.
How to protect yourself
- Use high-security, GPS-enabled barrier seals (e-seals) that provide a digital audit trail. See our glossary entry on container seals.
- Videotape the entire container loading and sealing process with clear timestamps.
- Use a third-party verification system to count and confirm cargo before the seal is applied. Our container load calculator helps you plan what should be inside.
Myth 6: "General average is for big shippers"
What is general average?
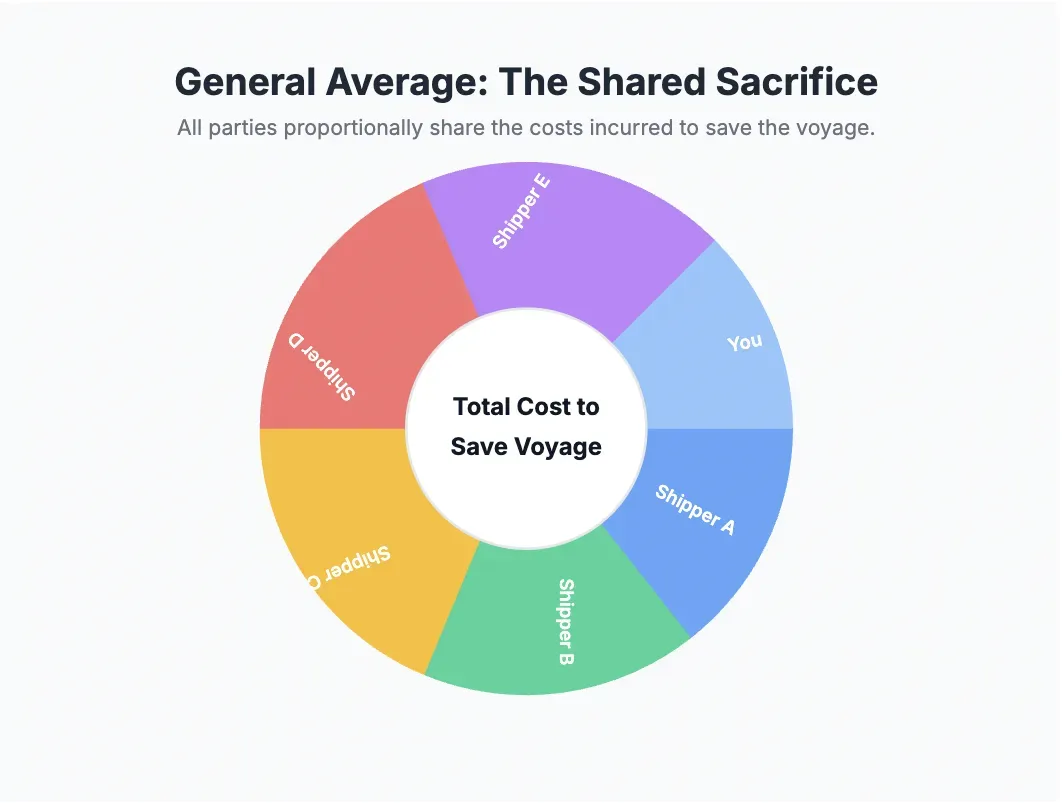
If a vessel is in peril (for example, from a fire or running aground), the captain may intentionally sacrifice some cargo (jettison) or incur extraordinary expenses (like hiring a salvage tug) to save the overall voyage. Under general average, all parties whose cargo survived the voyage must share the cost of the sacrifice in proportion to their cargo's value.
Reality: GA targets the unprepared
When the Ever Given blocked the Suez Canal in March 2021, its owner declared General Average on April 1. Every cargo owner on board, large or small, had to provide GA security before their cargo was released.
How GA works
- The carrier declares an emergency (fire, grounding).
- All shippers split the costs (yes, even you).
- No GA security? Your cargo is held until you provide it.
The only defense
- Insure your cargo. Standard cargo policies (Institute Cargo Clauses A, B and C) cover your GA contribution, and your insurer provides the GA guarantee the adjuster requires. That spares you from tying up your own company's cash in a deposit for months or even years while the final GA costs are calculated.
- Verify your insurer's GA process (some take weeks to issue a guarantee).
This is one of the most compelling reasons to buy cargo insurance. A standard policy covers your GA contribution and provides the security needed to get your cargo released promptly. The governing principles are set out in the York-Antwerp Rules.
Building a bulletproof insurance strategy
A robust strategy goes beyond simply buying a policy. It integrates insurance into a broader risk management framework.
- Risk assessment: Identify your primary vulnerabilities. Is it temperature-sensitive cargo? High-value goods prone to theft? Time-critical components?
- Coverage architecture: Use a layered approach.
- Primary cargo policy: for standard physical loss and damage.
- Endorsements: add specific coverage for war and strikes, riots and civil commotions (SR&CC), or delay.
- Contingent insurance: consider business interruption or DSU policies for critical supply chains.
- Prevention and documentation: The best claim is one you never have to file.
- Packaging: invest in proper blocking, bracing, and packaging.
- Vetting: use reputable carriers and forwarders with proven track records.
- Documentation: keep meticulous records, from the commercial invoice to the final signed proof of delivery.
FAQ: your top cargo insurance questions answered
If my cargo is delayed and damaged, which exclusion applies?
Insurers use "proximate cause" analysis. If delay caused the damage (for example, fruit rotting), it's excluded. If damage happened during a delay (for example, a container collision while stalled), it may be covered.
Can I buy separate "mysterious disappearance" coverage?
Rarely. Insurers view it as an unverifiable risk. Your best defense:
- Use numbered high-security bolt seals that meet ISO 17712.
- Require time-stamped loading videos from your supplier or loading supervisor.
How fast must I act after General Average is declared?
As soon as you receive the notice. Pass it to your insurer or broker right away so they can issue the GA guarantee. Until security is in place, your cargo stays on hold, and delays can:
- Add storage and other fees
- Put cargo at risk of being sold to cover charges if it goes unclaimed
Do temperature trackers guarantee claim approval?
No, but they're your best evidence.
- With a tracker: "Your cargo hit 50°C for 8 hours" means the claim can be proven.
- Without a tracker: "Prove it wasn't packed already warm."
Missed Part 1? Read about "all risk" coverage and common exclusions.
Final thoughts: myths die, your cargo shouldn't
The gap between a shipper's expectations and a policy's reality is where financial losses occur. This gap isn't a result of bad faith, but of the immense complexity of global trade.
The best claims are the ones you never file. Now that you know:
- Audit your policy for delay and GA gaps.
- Train staff on evidence collection.
- Assume nothing: test seals, trackers, and clauses.
For further industry standards and best practices, consult the International Union of Marine Insurance (IUMI).
Need to turn these insights into a workable strategy? Talk to our logistics specialists for a risk review and help choosing cover.
Get a quote for your shipment
Have a shipment to move? Send the origin, destination, cargo, and container size or weight. We reply with the rate, the routing and the services included.
